Blog

  • PM Jeevan Jyoti Bima Yojana 2026: ₹2 Lakh Life Insurance, ₹436 Premium, Eligibility and How to Apply

    PM Jeevan Jyoti Bima Yojana 2026: ₹2 Lakh Life Insurance, ₹436 Premium, Eligibility and How to Apply

    The PM Jeevan Jyoti Bima Yojana 2026 (PMJJBY) is a government-backed life insurance scheme for people who want basic financial protection for their families. It provides ₹2 lakh life insurance cover for death due to any cause at an annual premium of ₹436. People aged 18 to 50 years with an eligible bank or post office account can enrol.

    The policy runs for one year, from 1 June to 31 May, and can be renewed every year. The premium is deducted automatically from the account after the subscriber gives consent. Government of India+1

    What Is PM Jeevan Jyoti Bima Yojana?

    The Pradhan Mantri Jeevan Jyoti Bima Yojana was launched in 2015 as part of the government’s financial inclusion and social security initiatives.

    It is a one-year renewable term life insurance scheme. Its purpose is to provide affordable life cover to ordinary bank account holders, including people from low-income households.

    The scheme is administered through participating banks and post offices in partnership with the Life Insurance Corporation of India (LIC) and other approved life insurance companies.

    PMJJBY is not a savings account or investment plan. It does not build a maturity fund. Its main purpose is to provide a fixed insurance payment to the nominee if the insured subscriber dies while the policy is active and the claim meets the policy conditions.

    PM Jeevan Jyoti Bima Yojana Benefits 2026

    The main benefit is ₹2 lakh life insurance cover.

    FeatureDetails
    Insurance cover₹2 lakh
    Annual premium₹436
    Entry age18–50 years
    Policy period1 June to 31 May
    Payment methodAutomatic bank or post office debit
    RenewalYearly
    Cover typeDeath due to any cause, subject to policy conditions

    The insurance amount is paid to the registered nominee or eligible claimant. It can help a family manage essential expenses after the death of an earning member.

    Is the PMJJBY Premium Different for Late Registration?

    Yes. The official Department of Financial Services FAQ provides pro-rata premiums for eligible first-time applicants who join during the middle of a policy year.

    First-time enrolment periodPremium
    June–August₹436
    September–November₹342
    December–February₹228
    March–May₹114

    The full annual premium of ₹436 applies at renewal. These rates are based on the official scheme FAQ and should be checked again with the participating bank before enrolment. Government of India

    PM Jeevan Jyoti Bima Yojana Eligibility Criteria

    An applicant must meet the following conditions:

    • The applicant must be between 18 and 50 years old when joining.
    • The applicant must have an individual savings bank or post office account with a participating institution.
    • The applicant must give consent for enrolment.
    • The applicant must authorise automatic premium deduction.
    • The account must have enough money when the premium is due.

    A person with several bank accounts can enrol through only one eligible account. Opening multiple PMJJBY policies does not increase the maximum insurance benefit.

    A subscriber who joins before the maximum entry age can continue renewing the policy until reaching age 55, subject to annual renewal and the scheme rules. Government of India+1

    Important 30-Day Waiting Period

    A first-time subscriber is not covered for death from causes other than an accident during the first 30 days after enrolment. This is known as the lien period.

    For example, if a person joins the scheme and dies from a non-accidental cause within those first 30 days, the claim is not payable. Accidental death is treated differently under the scheme rules.

    The same 30-day condition applies when a person rejoins after leaving the scheme. Government of India+1

    Documents and Details Required

    Keep the following information ready when applying:

    • Active savings bank or post office account details.
    • Aadhaar or another KYC document accepted by the bank.
    • Registered mobile number.
    • Date of birth details.
    • Nominee’s name and relationship.
    • Signed enrolment and auto-debit consent form.

    The participating bank or post office may request additional information under its KYC process. Make sure the nominee’s details are correct. This is especially important because the nominee will normally submit the claim if the insured person dies.

    How to Apply for PM Jeevan Jyoti Bima Yojana Online or Offline

    There is no need to visit an insurance company’s office separately if your bank offers the scheme. Enrolment is handled through participating banks and post offices.

    Step 1: Check with your bank

    Contact your savings account branch and ask whether it offers PMJJBY enrolment. Post office account holders can also ask their post office about participation.

    Step 2: Request the enrolment form

    Ask for the PMJJBY application and consent form. You can also find forms through the official Jan Suraksha website.

    Step 3: Fill in your details

    Enter your name, date of birth, account number, nominee details and other requested information.

    Step 4: Give auto-debit consent

    Sign the authorisation allowing the bank or post office to deduct the annual premium. Read the declaration before signing.

    Step 5: Submit the application

    Submit the form through the bank’s accepted channel. Some banks also provide enrolment through internet banking or mobile banking.

    Step 6: Confirm enrolment

    Ask for an acknowledgement or confirmation message. Check your account statement to confirm that the premium has been deducted.

    Step 7: Save the policy details

    Keep your enrolment information and nominee details safely. Tell your family that the policy exists and explain where the information is kept.

    The policy should be renewed every year. Do not assume that cover will remain active if the account is closed or the premium cannot be collected. Government of India+1

    How to Claim the ₹2 Lakh Insurance Amount

    The nominee or eligible legal heir should contact the bank or post office where the subscriber enrolled.

    The usual process is:

    1. Inform the participating bank or post office about the subscriber’s death.
    2. Obtain the official PMJJBY claim-cum-discharge form.
    3. Complete the nominee or claimant details.
    4. Attach acceptable proof of death.
    5. Provide the nominee’s KYC document and bank account details.
    6. Submit the documents to the bank or post office for verification.
    7. Keep the claim acknowledgement and follow up with the institution.

    The official claim form asks for proof of death, claimant identity documents and bank account information. It recommends submitting the claim preferably within 30 days of death. Aadhaar and PAN details are listed as optional on the claim form. jansuraksha.gov.in

    Common Mistakes to Avoid

    • Assuming the policy provides ₹2 lakh for every type of financial loss.
    • Forgetting to renew the policy every year.
    • Keeping insufficient balance when the premium is due.
    • Giving incorrect nominee details.
    • Enrolling through more than one bank account.
    • Assuming non-accidental death is covered during the first 30 days after first-time enrolment.
    • Closing the linked bank account without checking the effect on insurance cover.
    • Failing to tell family members about the policy.

    Remember that PMJJBY is life insurance, not health insurance. It does not pay hospital bills or provide a maturity amount.

    Example: How PMJJBY Can Help a Family

    Suppose a 35-year-old shop assistant enrols in PMJJBY through a participating bank. The person pays the annual premium of ₹436 and names their spouse as nominee.

    If the subscriber dies while the cover is active and the claim meets the scheme conditions, the spouse can submit the claim documents. The nominee may receive ₹2 lakh after the insurer verifies and approves the claim.

    This is an illustrative example. It is not a guarantee of claim approval in every situation.

    Frequently Asked Questions

    1. How much insurance does PMJJBY provide?

    It provides ₹2 lakh life insurance cover for death due to any cause, subject to the policy conditions.

    2. What is the PMJJBY premium in 2026?

    The standard annual premium listed by the Department of Financial Services is ₹436. Pro-rata rates may apply to first-time enrolment during the policy year.

    3. Can a 52-year-old person join PMJJBY?

    No. The maximum entry age is 50 years. Existing eligible subscribers can continue renewal up to age 55 under the scheme rules.

    4. Is PMJJBY automatically renewed?

    The bank or post office can deduct the premium automatically if the subscriber has authorised it and the account has sufficient funds. Check that the renewal debit has taken place.

    5. Where can I apply for PMJJBY?

    Apply through a participating bank or post office. Official forms are available on jansuraksha.gov.in.

    Official Website and Next Step

    Visit the Department of Financial Services PMJJBY page for current premium details and scheme conditions. You can also download the forms from the Jan Suraksha portal.

    Before enrolling, check your age eligibility, nominee details and the policy’s 30-day waiting period.
  • PM Suraksha Bima Yojana 2026: ₹20 Premium, ₹2 Lakh Accident Insurance, Eligibility and Online Application

    PM Suraksha Bima Yojana 2026: ₹20 Premium, ₹2 Lakh Accident Insurance, Eligibility and Online Application

    The PM Suraksha Bima Yojana 2026 (PMSBY) offers low-cost personal accident insurance to eligible bank and post office account holders. For an annual premium of just ₹20, an enrolled person can receive ₹2 lakh cover for accidental death or permanent total disability. The scheme also provides ₹1 lakh for certain permanent partial disabilities.

    People aged 18 to 70 years can apply through a participating bank or post office. The premium is collected through automatic debit after the applicant gives consent. Government of India+1

    What Is PM Suraksha Bima Yojana?

    Pradhan Mantri Suraksha Bima Yojana is a government-supported personal accident insurance scheme launched in 2015.

    It was designed to make accident insurance affordable for ordinary people, including workers, small business owners, farmers and families with limited incomes.

    The scheme is managed through participating banks and post offices in partnership with approved general insurance companies. It provides protection against specified accidental death and permanent disability.

    PMSBY is a one-year renewable insurance policy. It is not a health insurance plan. It does not pay normal hospitalisation expenses, medicine bills or compensation for every temporary injury.

    PM Suraksha Bima Yojana Benefits and Premium 2026

    The annual premium is ₹20 per insured person.

    The insurance benefit depends on the type of accident-related loss.

    Accident-related eventInsurance benefit
    Accidental death₹2 lakh
    Permanent total disability covered under the rules₹2 lakh
    Specified permanent partial disability₹1 lakh
    Annual premium₹20

    The scheme defines permanent total disability through specific conditions. These include the total and irrecoverable loss of both eyes, the loss of use of both hands or feet, or a combination of the specified losses of sight and limb use.

    Permanent partial disability includes the total and irrecoverable loss of sight in one eye or loss of use of one hand or foot.

    A minor injury or temporary inability to work does not automatically qualify for a payment. The insurer checks the medical and accident documents against the scheme’s definitions. Government of India+1

    PM Suraksha Bima Yojana Eligibility Criteria

    To join PMSBY, a person must meet these basic conditions:

    • Be between 18 and 70 years old.
    • Hold an eligible individual savings bank or post office account.
    • Give consent to join the scheme.
    • Authorise automatic deduction of the annual premium.
    • Maintain sufficient balance for the premium debit.

    Both single and joint account holders can enrol if they meet the age and other conditions. However, one individual can obtain cover through only one bank or post office account, even if they have several accounts.

    The insurance cover ends or becomes restricted when the subscriber reaches age 70, closes the linked account or does not maintain enough balance for the premium. Government of India+1

    What Does PMSBY Not Cover?

    Understanding the limits is important before applying.

    PMSBY is designed for specified accidental death and permanent disability. It does not provide:

    • Reimbursement of ordinary hospitalisation expenses.
    • A payment for every temporary injury.
    • Compensation for a disability that does not meet the policy definition.
    • A death benefit for suicide.
    • Multiple insurance payments for enrolling through several accounts.

    The official FAQ states that accidental death or disability caused by natural calamities can also be covered when it meets the scheme’s definition. Death due to suicide is not covered. Government of India+1

    Documents and Information Required

    For enrolment, keep these details ready:

    • Bank or post office account number.
    • Aadhaar or other KYC information requested by the institution.
    • Active mobile number.
    • Date of birth.
    • Nominee details.
    • Signed application and auto-debit consent.

    The institution may already have some of your KYC details. Confirm which documents it needs before submitting the application.

    For a future claim, the nominee or insured person may need the claim form, accident details, medical records, proof of death or disability, claimant KYC and bank account details. The exact documents depend on whether the claim is for death or disability.

    How to Apply for PM Suraksha Bima Yojana Online

    You can apply through your participating bank or post office.

    Step 1: Contact your bank

    Ask whether your bank provides PMSBY enrolment. If you have a post office savings account, ask the post office about the scheme.

    Step 2: Request the PMSBY application form

    You can obtain the form from the institution or use the official Jan Suraksha forms page.

    Step 3: Enter your personal information

    Provide your name, date of birth, account number and nominee details.

    Step 4: Read the declaration

    Check the insurance conditions, age limit and policy period. Do not sign without understanding the automatic premium deduction.

    Step 5: Authorise automatic debit

    Give your consent for the annual premium to be deducted from the selected account.

    Step 6: Submit the form

    Submit it through your bank’s branch or digital channel, if available.

    Step 7: Confirm your enrolment

    Check for an acknowledgement or confirmation message. Review your account statement to verify the premium deduction.

    Step 8: Check renewal every year

    The insurance period normally runs from 1 June to 31 May. Keep enough money in the account when the next premium is due.

    New eligible entrants can join in later years. Their cover starts from the date the premium is debited. Government of India+1

    How to Claim PMSBY Accident Insurance

    If an enrolled person suffers a qualifying permanent disability, the insured person should contact the bank or post office and request the PMSBY claim form.

    If the insured person dies due to an accident, the nominee or eligible legal heir should approach the institution.

    The process generally involves:

    1. Informing the bank or post office about the accident.
    2. Obtaining the PMSBY claim-cum-discharge form.
    3. Recording the date, place and details of the accident.
    4. Providing proof of death or permanent disability.
    5. Attaching the required hospital and police records, where applicable.
    6. Providing the nominee’s or claimant’s KYC and bank details.
    7. Submitting the claim for verification.

    The official claim form recommends submission preferably within 30 days of the accident. For a vehicle accident, drowning or an incident involving a crime, police records may be required. For certain incidents such as a snake bite or fall from a tree, immediate hospital records may be used as supporting evidence under the scheme instructions. jansuraksha.gov.in+1

    Common Mistakes to Avoid

    • Assuming PMSBY covers normal medical expenses.
    • Believing every injury qualifies for ₹1 lakh or ₹2 lakh.
    • Forgetting to renew the insurance every year.
    • Enrolling through multiple accounts.
    • Providing incorrect nominee information.
    • Allowing the linked account to close.
    • Keeping insufficient funds for the annual premium.
    • Waiting too long to inform the bank after an accident.
    • Failing to preserve hospital or police documents.

    A ₹20 premium makes the scheme affordable, but it does not remove the need to understand the insurance conditions.

    Example: How PMSBY Can Support a Family

    Suppose a 42-year-old delivery worker enrols in PMSBY through a bank account and names their spouse as nominee.

    The worker pays the annual premium of ₹20. Later, the worker dies in a road accident while the cover is active. If the accident and claim documents satisfy the scheme conditions, the nominee may receive ₹2 lakh.

    If the worker instead suffers a qualifying permanent partial disability, the applicable benefit may be ₹1 lakh.

    This is an illustrative example. The insurer decides the claim after reviewing the evidence and policy conditions.

    Frequently Asked Questions

    1. What is the annual PMSBY premium?

    The official annual premium is ₹20 per person.

    2. How much insurance is available under PMSBY?

    The scheme provides ₹2 lakh for accidental death or specified permanent total disability and ₹1 lakh for specified permanent partial disability.

    3. What is the age limit for PMSBY?

    Eligible people aged 18 to 70 years can join.

    4. Does PMSBY cover hospital expenses?

    No. The scheme provides defined accident insurance benefits. It does not reimburse hospitalisation expenses.

    5. Where can I apply for PMSBY?

    Apply through a participating bank or post office. Forms and official information are available at jansuraksha.gov.in.

    Official Website and Next Step

    Read the official PMSBY information from the Department of Financial Services before enrolling.

    You can also visit the Jan Suraksha portal to download application and claim forms. Check your nominee details and confirm that the annual premium has been deducted successfully.

  • PM Ujjwala Yojana 2026: Free LPG Connection, ₹300 Refill Subsidy, Eligibility and Online Apply

    PM Ujjwala Yojana 2026: Free LPG Connection, ₹300 Refill Subsidy, Eligibility and Online Apply

    The PM Ujjwala Yojana 2026 (PMUY) helps eligible women from poor households get access to LPG cooking fuel. Under the scheme, an eligible woman can receive a deposit-free LPG connection, a free first refill and a free gas stove. The government provides connection assistance of ₹2,050 for a 14.2 kg cylinder or ₹1,300 for a 5 kg cylinder under the current PMUY portal details.

    For FY 2026–27, the government has also confirmed a ₹300 subsidy on the first four refills each year for eligible PMUY beneficiaries, with the support for 5 kg cylinders calculated proportionately. pmuy.gov.in+1

    What Is PM Ujjwala Yojana?

    Pradhan Mantri Ujjwala Yojana was launched in May 2016 by the Ministry of Petroleum and Natural Gas.

    The scheme aims to reduce the use of traditional cooking fuels such as firewood, dung cakes and other biomass fuels in poor households. It provides LPG connections in the name of eligible adult women.

    PMUY is currently being implemented through its Ujjwala 2.0 framework. The scheme remains active, and the official portal lists the application process, eligibility requirements, documents and distributor information.

    The government reported more than 10.56 crore connections under PMUY as of 23 September 2026. These are nationwide figures and do not mean every applicant is automatically eligible. pmuy.gov.in

    PM Ujjwala Yojana Benefits 2026

    The scheme provides financial assistance for a new LPG connection and certain initial equipment.

    1. Deposit-Free LPG Connection

    The current official portal lists government cash assistance of:

    Connection typeGovernment assistance
    14.2 kg LPG connection₹2,050
    5 kg LPG connection₹1,300

    For a 14.2 kg connection, the assistance covers:

    • Cylinder security deposit: ₹1,700.
    • Pressure regulator: ₹150.
    • LPG hose: ₹100.
    • Domestic Gas Consumer Card: ₹25.
    • Inspection, installation and demonstration charges: ₹75.

    The listed assistance for a 5 kg connection is ₹1,300. pmuy.gov.in

    2. Free First LPG Refill and Gas Stove

    The official PMUY portal states that beneficiaries receive the first LPG refill and hotplate or gas stove free of cost along with the deposit-free connection.

    This is an initial connection benefit. It should not be confused with the separate targeted subsidy paid on qualifying refills in later periods. pmuy.gov.in

    3. ₹300 Refill Subsidy in FY 2026–27

    The government confirmed on 7 June 2026 that eligible PMUY households receive a direct benefit transfer of ₹300 per 14.2 kg cylinder on the first four refills each year.

    For a 5 kg cylinder, the subsidy is proportionate to its capacity. The payment is transferred to the beneficiary’s bank account under the applicable process. The exact retail price depends on location and the price in force when the refill is booked. Press Information Bureau+1

    4. Cleaner Cooking for the Household

    LPG can reduce household exposure to smoke from traditional solid fuels when used as the main cooking fuel. It can also reduce the time spent collecting firewood and preparing traditional fuel.

    However, beneficiaries still need to plan for refill costs after using the free first refill and any applicable subsidy.

    PM Ujjwala Yojana Eligibility Criteria

    The main eligibility requirements are:

    • The applicant must be an adult woman aged 18 years or above.
    • She must belong to a poor household.
    • There must not be another LPG connection from any Oil Marketing Company in the same household.
    • The applicant must submit the prescribed deprivation declaration and required household documents.
    • The application must pass verification by the LPG distributor and relevant authorities.

    The PMUY portal identifies the applicant as the woman who receives the connection. A household that already has an LPG connection cannot obtain another PMUY connection simply by applying in another family member’s name. pmuy.gov.in+1

    Which Households May Qualify?

    The scheme’s prescribed eligibility framework includes categories such as:

    • Scheduled Caste households.
    • Scheduled Tribe households.
    • Pradhan Mantri Awas Yojana–Gramin households.
    • Most Backward Classes.
    • Antyodaya Anna Yojana households.
    • Tea and ex-tea garden tribes.
    • Forest dwellers.
    • Households in islands and river islands.
    • SECC-listed households.
    • Other poor households supported by the prescribed deprivation declaration.

    The distributor checks the documents and household details. Belonging to one of these categories does not remove the requirement to meet the other scheme conditions. pmuy.gov.in+1

    Documents Required for PM Ujjwala Yojana

    Prepare the following documents:

    • Applicant’s Aadhaar card.
    • Aadhaar cards of adult family members listed in the household document.
    • State ration card or another government document confirming family composition.
    • Address proof, if the address differs from Aadhaar.
    • Bank passbook copy or cancelled cheque.
    • KYC application form.
    • Prescribed deprivation declaration.
    • Migrant self-declaration, where applicable.

    The official portal provides special self-declaration forms for migrant applicants. A migrant woman who does not have the usual ration card or address document should check the prescribed Annexure I process rather than submitting an unrelated document. pmuy.gov.in+1

    How to Apply for PM Ujjwala Yojana Online

    Eligible women can apply through the official PMUY portal and the websites of the three major LPG companies.

    Step 1: Visit the official PMUY website

    Open pmuy.gov.in.

    Step 2: Select the new connection option

    Choose the option to apply for a new PMUY connection.

    Step 3: Select your LPG company

    The portal provides links for:

    • Indane.
    • Bharatgas.
    • HP Gas.

    Choose the company and application route that suits your location.

    Step 4: Enter applicant details

    Provide the applicant’s name, address, mobile number and other requested information.

    Step 5: Submit Aadhaar and household information

    Enter the Aadhaar and family details required for verification. Make sure the names match the household document.

    Step 6: Upload the required documents

    Submit the KYC form, ration card or accepted family document, bank details and deprivation declaration.

    Step 7: Choose the distributor

    Select an available LPG distributor or follow the online process provided by the oil marketing company.

    Step 8: Complete verification

    The distributor checks the application, household details and eligibility conditions. They may ask for clarification if the information is incomplete.

    Step 9: Complete the connection process

    After approval, follow the instructions for installation and receipt of the LPG connection, first refill and stove.

    You can also submit the application directly at your chosen LPG distributor instead of applying online. pmuy.gov.in+1

    How to Check PM Ujjwala Application Status

    After submitting your application:

    1. Keep the application reference number.
    2. Visit the LPG company’s customer portal.
    3. Use the available application or connection-status option.
    4. Enter the requested details.
    5. Check whether verification is pending, approved or requires correction.

    If the status does not change, contact the distributor where you submitted the application. You can also use the helpline numbers listed on the PMUY portal.

    Common Mistakes to Avoid

    • Applying when another LPG connection already exists in the household.
    • Using incorrect Aadhaar or ration card details.
    • Providing a bank account that is not in the applicant’s name.
    • Forgetting the deprivation declaration.
    • Ignoring the migrant self-declaration option when applicable.
    • Paying an unofficial agent for a guaranteed connection.
    • Assuming every future refill will be free.
    • Confusing the ₹300 refill subsidy with the initial connection assistance.
    • Failing to complete the required LPG KYC or verification process.

    Always obtain a receipt for any payment made to the authorised distributor. Do not share banking OTPs or PINs with anyone claiming to process the subsidy.

    Example: How a Woman Can Get an Ujjwala Connection

    Suppose an adult woman in a rural household does not have an LPG connection. Her household meets the poor-household criteria, and she has the required Aadhaar, family document and bank details.

    She applies through the PMUY portal and selects an LPG distributor. After verification and approval, she receives the eligible deposit-free connection, first refill and stove. If she continues to qualify for the refill subsidy, she can receive the applicable ₹300 benefit on the first four qualifying 14.2 kg refills in FY 2026–27.

    This is an illustrative example. Approval depends on the household’s eligibility and document verification.

    Frequently Asked Questions

    1. Who can apply for PM Ujjwala Yojana?

    An adult woman aged 18 or above from an eligible poor household can apply if there is no other LPG connection in the household and all scheme conditions are met.

    2. How much connection assistance is available?

    The current PMUY portal lists ₹2,050 for a 14.2 kg connection and ₹1,300 for a 5 kg connection.

    3. Is the first gas refill free?

    Yes. The official portal states that the first LPG refill and stove are provided free with the eligible new connection.

    4. How much is the Ujjwala refill subsidy in FY 2026–27?

    The government confirmed ₹300 per 14.2 kg cylinder for the first four refills each year. The support for 5 kg cylinders is proportionate.

    5. Where can I apply for PM Ujjwala Yojana?

    Visit pmuy.gov.in or apply through an authorised LPG distributor.

    Official Website and Next Step

    Visit the PM Ujjwala Yojana official portal to check eligibility, download the KYC and declaration forms, choose an LPG company and submit your application.

    For questions about the connection or subsidy, contact your LPG distributor or use the official PMUY helplines: 14438 for Ujjwala assistance, 14428 for toll-free support and 1906 for LPG emergencies.

  • PM Shram Yogi Maandhan Yojana 2026: ₹3,000 Monthly Pension, Eligibility, Contribution and Registration

    PM Shram Yogi Maandhan Yojana 2026: ₹3,000 Monthly Pension, Eligibility, Contribution and Registration

    The PM Shram Yogi Maandhan Yojana 2026 (PM-SYM) is a voluntary pension scheme for eligible unorganised workers in India. It offers an assured monthly pension of ₹3,000 after the subscriber reaches 60 years of age. Workers contribute a fixed amount every month, while the Central Government makes an equal matching contribution.

    Eligible workers aged 18 to 40 years with a monthly income of ₹15,000 or less can apply. They must not be covered by EPFO, ESIC or the National Pension System and must not be income-tax payers. labour.gov.in+1

    What Is PM Shram Yogi Maandhan Yojana?

    The Pradhan Mantri Shram Yogi Maandhan scheme was introduced to provide old-age financial security to workers in the unorganised sector.

    Many workers earn through daily wages, small businesses, home-based jobs or self-employment. They may not have access to an employer-funded pension plan.

    PM-SYM provides a structured way for eligible workers to save towards retirement. The worker contributes monthly until age 60, and the Central Government matches the contribution.

    The scheme is administered by the Ministry of Labour and Employment. The Life Insurance Corporation of India acts as the pension fund manager, while Common Service Centres help with enrolment. labour.gov.in+1

    PM Shram Yogi Maandhan Yojana Benefits 2026

    The main benefit is a minimum assured pension of ₹3,000 per month after age 60, provided the subscriber fulfils the scheme’s contribution conditions.

    Other important benefits include:

    • Equal matching contribution from the Central Government.
    • Monthly pension after reaching age 60.
    • Family pension for the spouse after the subscriber starts receiving pension.
    • Defined exit and withdrawal provisions.
    • Enrolment support through Common Service Centres.

    Government Matching Contribution

    PM-SYM follows a 50:50 contribution structure. The worker pays an age-based monthly contribution, and the government contributes an equal amount.

    For example, a worker who joins at age 30 pays ₹105 per month. The Central Government contributes another ₹105, making the total monthly contribution ₹210. labour.gov.in+1

    Monthly Contribution by Joining Age

    The worker’s monthly contribution increases with the age at which they join.

    Age when joiningWorker pays monthlyGovernment matches
    18 years₹55₹55
    20 years₹61₹61
    25 years₹80₹80
    30 years₹105₹105
    35 years₹150₹150
    40 years₹200₹200

    The full schedule includes different amounts for each entry age. The worker continues paying the prescribed contribution until age 60. labour.gov.in+1

    Family Pension Benefit

    If a subscriber dies after starting to receive the pension, the spouse is entitled to 50% of the pension as family pension under the scheme rules.

    This benefit applies to the spouse. It is not a separate full ₹3,000 pension for every family member.

    If the subscriber dies before age 60 after making regular contributions, the spouse may continue the scheme by paying the required contributions or exit according to the prescribed withdrawal rules. labour.gov.in+1

    PM Shram Yogi Maandhan Yojana Eligibility Criteria

    An applicant must satisfy all the following major conditions:

    • Must be an unorganised worker.
    • Must be between 18 and 40 years old when joining.
    • Monthly income must be ₹15,000 or less.
    • Must not be covered under EPFO.
    • Must not be covered under ESIC.
    • Must not be covered under the National Pension System.
    • Must not be an income-tax payer.
    • Must have a savings bank or Jan Dhan account.
    • Must have an Aadhaar number and mobile phone.

    The scheme is intended for workers such as:

    • Street vendors.
    • Domestic workers.
    • Agricultural labourers.
    • Construction workers.
    • Rickshaw pullers.
    • Cobblers.
    • Home-based workers.
    • Washermen.
    • Small self-employed workers.
    • Brick kiln and handloom workers.
    • Other eligible unorganised workers.

    A salaried person covered by EPFO or ESIC should not assume they can join PM-SYM simply because their monthly income is low. The scheme has specific social security exclusions. labour.gov.in+1

    Documents Required for PM-SYM Registration

    Prepare these items before visiting a Common Service Centre:

    • Aadhaar card.
    • Savings bank account passbook or Jan Dhan account details.
    • Active mobile number.
    • Date of birth details.
    • Information about occupation and monthly income.
    • Nominee or spouse details, as requested during enrolment.

    The official process uses Aadhaar and bank account information. Eligible workers can register on a self-certification basis through the prescribed process. The enrolment centre may ask for additional details to complete the registration.

    How to Apply for PM Shram Yogi Maandhan Yojana Online

    Eligible workers can use the Maandhan portal or visit a Common Service Centre.

    Step 1: Visit the official portal

    Open maandhan.in and select the PM-SYM service.

    Step 2: Check your eligibility

    Confirm your age, monthly income and employment category. Make sure you are not covered under the excluded pension and social security schemes.

    Step 3: Keep Aadhaar and bank details ready

    You will need your Aadhaar number, mobile number and savings or Jan Dhan account information.

    Step 4: Visit a Common Service Centre if needed

    If you cannot complete the process online, visit your nearest CSC with your documents.

    Step 5: Complete Aadhaar authentication

    The CSC operator will use the prescribed Aadhaar-based verification process.

    Step 6: Enter personal and occupation details

    Provide your name, date of birth, occupation, income information, bank details and other required information.

    Step 7: Check your monthly contribution

    The system calculates the contribution based on your age at enrolment. Review the amount before confirming.

    Step 8: Pay the first contribution

    The first month’s contribution is paid at the enrolment centre. Obtain a receipt.

    Step 9: Authorise automatic debit

    Sign the required mandate so that future monthly contributions can be collected from your bank account.

    Step 10: Collect your enrolment details

    Keep the PM-SYM account information and pension card safely. Check that the bank debit begins correctly.

    The Ministry’s published enrolment guidance confirms that workers can register through CSCs and the Maandhan portal. labour.gov.in+1

    What Happens If You Stop Paying Contributions?

    PM-SYM is a contributory pension scheme. Regular contributions are important.

    If a subscriber misses contributions, the scheme allows the account to be regularised by paying outstanding dues along with any applicable penalty decided under the rules.

    The scheme also has exit provisions. If a subscriber exits before completing 10 years, the subscriber’s own contribution is returned with savings bank interest. If the subscriber exits after 10 years but before age 60, the subscriber’s contribution is returned with the applicable accumulated interest under the scheme’s rules. labour.gov.in+1

    Before leaving the scheme, ask the CSC or official helpdesk to explain the amount payable and the effect on future pension rights.

    Common Mistakes to Avoid

    • Applying after reaching age 40.
    • Hiding EPFO, ESIC or NPS coverage.
    • Giving incorrect monthly income information.
    • Entering an incorrect date of birth.
    • Providing the wrong bank account number.
    • Ignoring missed contribution messages.
    • Assuming the government pays the entire contribution.
    • Believing the pension starts immediately after registration.
    • Treating the ₹3,000 pension as a benefit available without regular contributions.

    The pension begins only after the subscriber reaches 60 and satisfies the scheme requirements.

    Example: How a 30-Year-Old Worker Can Join PM-SYM

    Suppose a 30-year-old tailor earns ₹12,000 per month through an unorganised business. The tailor is not covered under EPFO or ESIC, is not an income-tax payer and meets the other eligibility conditions.

    The tailor joins PM-SYM through a CSC. The monthly contribution is ₹105 from the worker and ₹105 from the government.

    The worker continues making the required contributions until age 60. After meeting the scheme conditions, the subscriber becomes eligible for the assured monthly pension of ₹3,000.

    This is an illustrative example. Actual eligibility and pension rights depend on enrolment and continued compliance with the rules.

    Frequently Asked Questions

    1. How much pension is available under PM-SYM?

    Eligible subscribers receive an assured pension of ₹3,000 per month after reaching age 60.

    2. Who can apply for PM Shram Yogi Maandhan?

    Eligible unorganised workers aged 18 to 40 years with monthly income up to ₹15,000 can apply, subject to the other conditions.

    3. How much does the worker pay every month?

    The contribution ranges from ₹55 to ₹200 per month, depending on the age at which the person joins.

    4. Does the government also contribute?

    Yes. The Central Government makes an equal matching contribution to the worker’s prescribed monthly contribution.

    5. Where can I register for PM-SYM?

    Visit maandhan.in or go to a nearby Common Service Centre.

    Official Website and Next Step

    Visit the Maandhan portal or read the Ministry of Labour and Employment’s PM-SYM information.

    If you are an eligible unorganised worker, check your age and income conditions first. Then visit a CSC with your Aadhaar card, mobile phone and bank passbook to understand your monthly contribution before joining.

  • Atal Pension Yojana 2026: Eligibility, Pension Benefits, Contribution and How to Apply

    Atal Pension Yojana 2026: Eligibility, Pension Benefits, Contribution and How to Apply

    Planning for retirement is important, even if you work in a small business, run a shop or earn a daily wage. Atal Pension Yojana is a Government of India pension scheme that helps eligible citizens build a regular income for old age. Subscribers can choose a guaranteed minimum monthly pension of ₹1,000, ₹2,000, ₹3,000, ₹4,000 or ₹5,000 after turning 60. The amount depends on the pension option selected and the contributions paid before retirement. Here is how the scheme works, who can join and how to open an account.

    What is Atal Pension Yojana?

    Atal Pension Yojana, also known as APY, is a voluntary pension scheme launched by the central government in 2015. It is administered by the Pension Fund Regulatory and Development Authority (PFRDA).

    The scheme is designed especially for people who may not have a formal company pension. This includes workers in the unorganised sector, shopkeepers, small traders and other eligible citizens.

    A subscriber makes regular contributions from a savings bank account or post office savings account. Contributions continue until the subscriber reaches 60 years of age. After that, the subscriber receives the selected minimum pension every month.

    APY is not a one-time government payment. It is a contribution-based pension plan with a government-guaranteed minimum pension under its rules. The official PFRDA APY page explains its features and enrolment options. PFRDA+1

    Atal Pension Yojana benefits: How much pension can you receive?

    The main benefit is a guaranteed minimum monthly pension after the subscriber reaches 60.

    Pension optionMonthly pension after age 60
    Option 1₹1,000
    Option 2₹2,000
    Option 3₹3,000
    Option 4₹4,000
    Option 5₹5,000

    The subscriber must select one of these options while joining. The contribution amount depends on three factors:

    • The subscriber’s age when the account is opened.
    • The monthly pension option selected.
    • Whether contributions are paid monthly, quarterly or half-yearly.

    Joining at a younger age generally means a lower contribution for the same pension option because the subscriber has more time to contribute before turning 60. PFRDA provides an age-wise contribution chart in its official APY information. Check that chart before choosing an option rather than relying on an estimate from an unofficial website. PFRDA+1

    There are also benefits for the family:

    • Pension for the spouse: After the subscriber’s death, the spouse is entitled to receive the same monthly pension for the rest of their life.
    • Pension wealth for the nominee: After both the subscriber and spouse have died, the nominee receives the pension wealth accumulated under the scheme, according to its rules.

    These benefits make APY a long-term family pension arrangement, not simply an individual savings account. PFRDA+1

    Who can apply for Atal Pension Yojana?

    You must meet the following conditions to open a new APY account:

    1. You must be an Indian citizen.
    2. Your age must be between 18 and 40 years.
    3. You must have a savings bank account or post office savings bank account.
    4. You must not be an income-tax payer on the date you apply.

    Since 1 October 2022, a person who is or has been an income-tax payer under the Income-tax Act is not eligible to open a new APY account.

    There is an important distinction for existing subscribers. If a person joined APY before the restriction and later becomes an income-tax payer, the account can continue under the applicable rules. Government employees and existing NPS subscribers are not automatically excluded if they meet the other APY conditions. PFRDA+1

    Documents and details required

    Keep these details ready before visiting your bank or post office:

    • Savings bank or post office account details.
    • Mobile number for account updates.
    • Aadhaar details for identification.
    • Date of birth and other personal information.
    • Spouse details, if married.
    • Nominee details.

    Providing Aadhaar at the time of enrolment is described by PFRDA as desirable rather than mandatory. However, Aadhaar details must be furnished later if they were not provided during enrolment. Providing nominee details is mandatory. If you are married, your spouse is the default nominee under the scheme rules. PFRDA

    How to apply for Atal Pension Yojana

    You can open an account through a participating bank or post office. Online enrolment is also available through the eAPY facility.

    Step 1: Check your eligibility. Confirm your age, citizenship, tax status and savings account details.

    Step 2: Choose your pension option. Decide whether you want a minimum monthly pension of ₹1,000, ₹2,000, ₹3,000, ₹4,000 or ₹5,000.

    Step 3: Check the contribution amount. Use the official contribution chart to understand how much will be deducted at your age for your selected pension.

    Step 4: Complete the registration form. Visit the bank or post office holding your savings account. Fill in the APY registration form with your personal details, pension choice and nominee information.

    Step 5: Authorise automatic contributions. Choose monthly, quarterly or half-yearly contributions. The amount will be collected automatically from your linked account.

    Step 6: Keep your acknowledgement. Save the enrolment confirmation and account details. You can use the official PFRDA APY website to find scheme information and online enrolment links. PFRDA+1

    Common mistakes to avoid

    • Joining after the age limit: You cannot open a new account after completing 40 years of age.
    • Ignoring the income-tax rule: Check your tax-payer status before applying.
    • Selecting a pension without checking contributions: Compare the contribution amount with your regular income.
    • Keeping insufficient bank balance: Missed automatic deductions can affect account continuity.
    • Entering incorrect nominee details: Check names and other information before submitting the form.
    • Opening multiple accounts: One person can hold only one APY account.

    A simple example

    Suppose a 25-year-old shopkeeper wants a pension after retirement. He checks the official contribution chart and chooses the ₹3,000 monthly pension option. His bank calculates the contribution based on his age and selected frequency. He authorises automatic deductions and keeps enough money in the account on the due dates.

    If he continues contributing according to the scheme rules until age 60, he becomes eligible for the selected minimum pension. If he dies after pension payments begin, his spouse is entitled to the same monthly pension under the scheme. This is an illustrative example, not a promise of a particular contribution amount.

    Frequently asked questions

    1. Can I join APY at the age of 35?

    Yes. An eligible Indian citizen can join between 18 and 40 years, provided the other conditions are met.

    2. Can an income-tax payer open a new APY account?

    No. A person who is or has been an income-tax payer on the application date is not eligible to open a new account under the rule effective from 1 October 2022.

    3. Is Aadhaar compulsory for APY enrolment?

    PFRDA says Aadhaar is desirable but not mandatory at the time of enrolment. However, the details must be furnished later if they were not supplied initially.

    4. Can I change my pension option later?

    Yes. PFRDA allows subscribers to upgrade or downgrade their selected pension amount within the permitted annual change window. Check the current process with your bank or the APY service provider.

    5. What happens if the subscriber dies before turning 60?

    The spouse may choose to continue contributing to the account until the original subscriber would have reached 60, or the accumulated corpus may be returned to the spouse or nominee under the scheme rules. PFRDA+2

    Apply through the official website

    If you meet the conditions, compare the pension options and contribution amounts before enrolling. Start with the official PFRDA Atal Pension Yojana page, or visit the bank or post office where you hold your savings account. Make sure you understand the automatic deduction and keep your nominee details updated.

  • PM Suraksha Bima Yojana 2026: Benefits, Eligibility, ₹20 Premium and Application Process

    PM Suraksha Bima Yojana 2026: Benefits, Eligibility, ₹20 Premium and Application Process

    An accident can affect a family’s finances in a matter of seconds. PM Suraksha Bima Yojana is a low-cost personal accident insurance scheme that provides financial support in the event of specified accidental death or permanent disability. Eligible account holders can join by paying an official annual premium of ₹20 through auto-debit. The scheme offers up to ₹2 lakh for accidental death or specified total permanent disability and ₹1 lakh for certain partial permanent disabilities. Here is what the cover includes, who can enrol and how to apply.

    What is PM Suraksha Bima Yojana?

    Pradhan Mantri Suraksha Bima Yojana, or PMSBY, is a one-year personal accident insurance scheme. It is renewable each year and is available through participating banks and post offices in partnership with approved general insurance companies.

    Unlike life insurance that covers death from different causes, this scheme focuses on accidental death and specified permanent disabilities. The accident must meet the scheme’s definition: a sudden, unforeseen and involuntary event caused by external, violent and visible means.

    The scheme does not provide a general hospitalisation allowance or reimburse routine medical expenses. Its benefit is linked to the specific death and disability conditions described in the policy. The Department of Financial Services publishes the official scheme details and frequently asked questions. Government of India+1

    PM Suraksha Bima Yojana benefits and annual premium

    The current official annual premium is ₹20 per member. It is deducted from the subscriber’s linked bank or post office account through an auto-debit arrangement after consent.

    The benefit depends on the nature of the accident:

    Accidental outcomeInsurance benefit
    Death₹2 lakh
    Total and irrecoverable loss of both eyes, both hands or both feet, or the specified combination of one eye and one hand or foot₹2 lakh
    Total and irrecoverable loss of sight in one eye, or loss of use of one hand or one foot₹1 lakh

    These are defined benefit categories. A temporary injury, ordinary fracture or partial loss of working ability does not automatically qualify for payment. The disability must meet the scheme’s stated definition and be supported by the required records. Government of India+1

    What accidents are covered?

    The scheme covers qualifying accidental death or disability. The official FAQ also states that qualifying events caused by natural calamities, such as floods or earthquakes, can be covered because they may fall within the accident definition.

    However, suicide is not covered. The FAQ also makes clear that PMSBY does not pay hospitalisation expenses after an accident. If a person suffers a disability that does not match the listed permanent disability categories, no benefit is payable under those categories. Government of India+1

    Who can apply for PM Suraksha Bima Yojana?

    The main eligibility conditions are simple:

    • You must be between 18 and 70 years of age.
    • You must hold an eligible individual savings bank or post office account.
    • You must give consent to join the scheme.
    • You must authorise automatic deduction of the annual premium.

    Both single and joint account holders can enrol if they meet the conditions. Each eligible holder of a joint account may join separately and pay the premium for their own cover.

    If you have several bank or post office accounts, you can enrol through only one account. Duplicate enrolment does not provide multiple payouts. The cover can end if the subscriber reaches the age limit, closes the linked account or does not maintain enough balance for the premium deduction. Government of India+1

    Documents and information required

    Keep the following information ready:

    • Your bank or post office account details.
    • Personal details, including date of birth.
    • Mobile number and contact information.
    • Nominee details.
    • PMSBY enrolment form.
    • Consent and auto-debit authorisation.

    The bank or post office may ask you to update KYC details if its records are incomplete. The enrolment form and consent documents are retained by the participating institution and may be required by the insurer during a claim. Government of India

    How to apply for PM Suraksha Bima Yojana

    PMSBY enrolment is handled through participating banks and post offices. Some institutions also provide digital enrolment.

    Step 1: Confirm your age and account eligibility. Check that you are between 18 and 70 years old and have an eligible account.

    Step 2: Contact your bank or post office. Ask for the PMSBY enrolment form or check the institution’s internet banking and mobile banking services.

    Step 3: Read the benefit conditions. Understand the difference between accidental death, total permanent disability and the specified partial disability categories.

    Step 4: Complete the form. Enter your personal information and nominee details carefully.

    Step 5: Give auto-debit consent. Authorise the annual ₹20 premium deduction from your chosen account.

    Step 6: Confirm enrolment. Check your account statement or obtain confirmation from the bank or post office. Save the acknowledgement and nominee information.

    The official rules are available on the Department of Financial Services PMSBY page. The department states that new eligible people can also join in later years, and risk cover starts from the date the premium is debited. Government of India+1

    What should a nominee do after an accident?

    If the subscriber dies in an accident, the nominee or legal heir should contact the bank or post office through which the policy was enrolled. The institution can explain the claim form and documents required by the insurer.

    For road, rail and similar vehicle accidents, drowning or deaths involving a crime, the official FAQ says the incident should be reported to the police. For events such as a snake bite or fall from a tree, the cause should be supported by immediate hospital records.

    A disability claim is paid to the insured subscriber’s bank account. A death claim is paid to the nominee or legal heir’s bank account, as applicable. Keep copies of the enrolment record and relevant accident documents. Government of India+1

    Common mistakes to avoid

    • Assuming every injury qualifies: The scheme pays only for the listed disability categories.
    • Expecting hospital bills to be reimbursed: PMSBY is not a medical expenses policy.
    • Enrolling through multiple accounts: Only one valid cover is recognised for a person.
    • Allowing the account to become inactive: Insufficient funds can interrupt cover.
    • Forgetting to update nominee information: Incorrect details can make claim handling harder.
    • Assuming the cover starts before premium deduction: Confirm the actual deduction and enrolment status.

    An illustrative example

    Imagine a 45-year-old delivery worker who joins the scheme through his bank. He authorises the ₹20 annual premium and receives confirmation of enrolment. Later, he suffers an accident that results in the permanent and irrecoverable loss of sight in one eye. If the injury meets the scheme’s definition and the claim is supported by the required documents, the applicable benefit is ₹1 lakh.

    This example is only an illustration. The insurer decides claims based on the policy conditions and documentary evidence.

    Frequently asked questions

    1. What is the PMSBY premium?

    The official annual premium is ₹20 per member, collected through auto-debit from the linked account.

    2. How much is paid for accidental death?

    The scheme provides ₹2 lakh for qualifying accidental death.

    3. Can a 65-year-old person join?

    Yes, if the person meets the other conditions and has not crossed the maximum entry age of 70.

    4. Does PMSBY cover hospital expenses?

    No. The scheme does not reimburse hospitalisation expenses after an accident.

    5. Can I receive a benefit for any partial disability?

    No. Only the specified permanent disability categories qualify. Other partial disabilities do not automatically receive a payment. Government of India+1

    Check the official website before enrolling

    If you meet the age and account conditions, contact your participating bank or post office to enrol. Read the official PMSBY information, confirm the ₹20 premium deduction and make sure your nominee details are correct. Keep the enrolment acknowledgement so your family can find the policy information if it is ever needed.

  • PM Jeevan Jyoti Bima Yojana 2026: Benefits, Eligibility, Premium and How to Apply

    PM Jeevan Jyoti Bima Yojana 2026: Benefits, Eligibility, Premium and How to Apply

    A family’s income can become uncertain if its main earning member dies unexpectedly. PM Jeevan Jyoti Bima Yojana offers eligible bank and post office account holders a simple way to obtain life insurance cover. The scheme provides ₹2 lakh to the nominee if the insured subscriber dies during the active cover period, subject to policy conditions. The annual premium is ₹436, collected through automatic deduction. This guide explains the cover, age limits, enrolment process and important conditions to check before joining.

    What is PM Jeevan Jyoti Bima Yojana?

    Pradhan Mantri Jeevan Jyoti Bima Yojana, commonly called PMJJBY, is a one-year renewable term life insurance scheme supported by the Government of India.

    It is administered through the Life Insurance Corporation of India (LIC) and other participating life insurance companies in partnership with banks and post offices. The bank or post office acts as the point through which eligible account holders enrol and pay the premium.

    The scheme is meant to provide basic financial protection to a family. It is not a savings account, investment plan or maturity-benefit policy. The main benefit is payable when the insured subscriber dies during the valid insurance period and the claim meets the scheme conditions. Government of India+1

    PM Jeevan Jyoti Bima Yojana benefits and premium

    The scheme provides a life insurance cover of ₹2 lakh on the death of an insured subscriber due to any cause, subject to the applicable conditions.

    The official annual premium is ₹436 per subscriber. It is collected through auto-debit from the linked bank or post office account after the subscriber gives consent.

    The cover normally runs from 1 June to 31 May and must be renewed every year. If the account holder joins for the first time during the middle of the policy year, the official premium schedule allows a pro-rata amount:

    First-time enrolment periodPremium
    June to August₹436
    September to November₹342
    December to February₹228
    March to May₹114

    The full annual premium of ₹436 is payable at renewal, according to the current Department of Financial Services information. Premiums and policy conditions can be revised by the government, so check the latest bank notice before authorising a deduction. Government of India+1

    Important 30-day waiting period

    First-time subscribers should understand the 30-day lien period. For a new enrolment, a death from a cause other than an accident during the first 30 days is not covered. Accidental death is treated differently and is covered from the date of joining, subject to the policy terms.

    This condition also applies to people who rejoin after leaving the scheme. Do not assume that paying the premium removes the waiting period for non-accidental death. Government of India+1

    Who is eligible for PM Jeevan Jyoti Bima Yojana?

    The main eligibility conditions are:

    • You must be between 18 and 50 years old when you first enrol.
    • You must hold an eligible individual savings bank or post office account.
    • You must give consent for enrolment and automatic premium deduction.
    • You can join through only one bank or post office account, even if you hold several accounts.

    Joint account holders can each enrol if they independently meet the eligibility conditions and pay the applicable premium. The cover can continue through annual renewals up to the age of 55, subject to the scheme conditions. Government of India+1

    Documents and details to keep ready

    The bank or post office will guide you through its enrolment process. Keep these items available:

    • Bank or post office account number.
    • Mobile number and current contact details.
    • Nominee’s name and required personal details.
    • Completed PMJJBY enrolment and consent form.
    • Auto-debit authorisation.
    • KYC details already recorded with your bank or post office.

    The bank or post office retains the enrolment and auto-debit authorisation. It may ask for additional information if its records need updating. Make sure the nominee information is correct because the nominee is the person who may need to submit a claim later. Government of India

    How to apply for PM Jeevan Jyoti Bima Yojana

    You can enrol through a participating bank or post office. Some institutions also provide digital enrolment through internet banking or mobile banking.

    Step 1: Check your age. Confirm that you are within the entry age range of 18 to 50 years.

    Step 2: Check your account. Make sure you have an eligible individual savings account and that it is active.

    Step 3: Contact your bank or post office. Ask whether PMJJBY enrolment is available through the branch, mobile banking or internet banking.

    Step 4: Complete the consent form. Provide your personal information and nominee details. Read the declaration carefully before signing.

    Step 5: Authorise the premium deduction. Confirm the amount that will be debited. If you are joining during the policy year for the first time, ask the bank to confirm the applicable pro-rata premium.

    Step 6: Save the confirmation. Keep the acknowledgement, policy or enrolment reference, and the bank’s confirmation of premium deduction.

    You can read the official rules on the Department of Financial Services PMJJBY page. There is no need to pay an unknown agent to enrol you. Government of India+1

    Common mistakes to avoid

    • Assuming the cover starts without confirmation: Check that the premium has actually been debited and enrolment has been recorded.
    • Ignoring the 30-day lien period: Non-accidental death during this period is not covered for a first-time or rejoining subscriber.
    • Using multiple bank accounts: Duplicate enrolments do not increase the total cover beyond the scheme limit.
    • Forgetting annual renewal: Keep sufficient funds in the account when the renewal premium is due.
    • Leaving nominee details blank or incorrect: Check the nominee’s name and contact information.
    • Confusing insurance with savings: PMJJBY does not promise a maturity amount simply because you paid premiums for several years.

    An illustrative example

    Consider a 32-year-old tailor who has a savings account and wants basic life cover. She enrols through her bank, gives consent for auto-debit and names a family member as nominee. After the bank confirms her enrolment and premium deduction, the policy provides the stated ₹2 lakh death cover during the valid insurance period, subject to its conditions.

    If she later changes her bank account, she should contact the bank about the effect on the policy and ensure that the renewal arrangement remains valid. This example is illustrative and does not represent a real claim or guarantee of acceptance.

    Frequently asked questions

    1. What is the PMJJBY premium in 2026?

    The official annual premium is ₹436. First-time subscribers joining during the year may pay a pro-rata premium depending on the month of enrolment.

    2. How much insurance cover does the scheme provide?

    It provides ₹2 lakh on the insured subscriber’s death, subject to the policy terms and conditions.

    3. Can a 52-year-old person join for the first time?

    No. New enrolment is available only to people aged 18 to 50. Existing subscribers may continue renewing within the scheme’s permitted conditions up to age 55.

    4. Is death due to illness covered?

    The scheme covers death due to any cause, subject to its conditions. However, non-accidental death during the first 30 days after first enrolment or rejoining is not covered.

    5. Can I join PMJJBY through two bank accounts?

    No. A person can join through only one eligible bank or post office account. Duplicate enrolment does not create additional cover. Government of India+1

    Where to check the official rules

    Before enrolling, read the latest information on the Department of Financial Services PMJJBY website. Then contact your bank or post office to complete the consent form, verify the premium and confirm that the nominee details have been recorded correctly.

  • Kisan Credit Card Yojana 2026: Eligibility, Loan Limit, Interest Rate and How to Apply

    Kisan Credit Card Yojana 2026: Eligibility, Loan Limit, Interest Rate and How to Apply

    Farmers often need money before harvest to buy seeds, fertilisers, feed, fuel and other farm supplies. Kisan Credit Card Yojana helps eligible farmers access credit through banks without applying for a separate short-term loan every time they need funds. The card can support crop cultivation, post-harvest expenses and certain allied activities. The actual loan limit and interest rate depend on the farming activity, bank assessment and applicable government support. This guide covers eligibility, documents, application steps and important points to check before borrowing.

    What is Kisan Credit Card Yojana?

    The Kisan Credit Card (KCC) scheme was introduced in 1998 to make agricultural credit easier to access. It provides a flexible credit facility through participating banks and cooperative institutions.

    A KCC is not a cash grant. It is a bank credit facility that must be repaid according to the agreed terms. The farmer can use the sanctioned amount for eligible agricultural needs, including:

    • Buying seeds, fertilisers and other crop inputs.
    • Meeting cultivation expenses.
    • Paying post-harvest and marketing costs.
    • Meeting certain household consumption needs.
    • Maintaining farm equipment and other agricultural assets.
    • Supporting eligible allied activities such as dairy, poultry and fisheries.

    The card may be issued with a RuPay-enabled payment facility, depending on the bank. The government continues to support the scheme through the banking system and the Modified Interest Subvention Scheme (MISS). Press Information Bureau+1

    Kisan Credit Card loan limit and interest support

    There is no single loan amount that every farmer receives. Banks assess the credit requirement using factors such as:

    • The area of land being cultivated.
    • The crops grown and their seasonal needs.
    • The local scale of finance for each crop.
    • The expected cost of cultivation.
    • Eligible allied activities and repayment capacity.

    A PIB backgrounder dated 11 March 2026 reported that the government had enhanced the crop-loan limit under MISS from ₹3 lakh to ₹5 lakh for 2025–26. It also reported an increase in the credit limit for fisheries and allied activities from ₹2 lakh to ₹5 lakh, and a collateral-free credit limit of ₹2 lakh per borrower, effective from 1 January 2025. Press Information Bureau+1

    What interest rate should farmers expect?

    The same PIB update says short-term agricultural loans up to ₹3 lakh were available at 7% interest, with an additional 3% prompt repayment incentive for eligible farmers who repay on time. This can reduce the effective interest rate to 4% for qualifying loans.

    There is an important detail here: the PIB backgrounder reports a ₹5 lakh crop-loan limit under MISS but separately describes the 7% rate and 3% repayment incentive for loans up to ₹3 lakh. Do not assume that the 4% effective rate applies to the full ₹5 lakh amount. The current year’s rules, the type of loan and the lender’s sanction terms matter.

    For example, SBI’s published KCC product information lists a 7% rate up to ₹3 lakh, subject to government interest support, and states that the prompt repayment incentive applies up to ₹3 lakh. Rates and conditions can change, so ask your bank for the applicable written terms before accepting the facility. Press Information Bureau+1

    Who is eligible for a Kisan Credit Card?

    The scheme is open to different types of eligible farmers and farming groups. These include:

    1. Individual farmers who own and cultivate land.
    2. Joint borrowers who are owner-cultivators.
    3. Tenant farmers.
    4. Oral lessees and sharecroppers.
    5. Self Help Groups (SHGs) of farmers.
    6. Joint Liability Groups (JLGs), including groups of tenant farmers and sharecroppers.

    The scheme is not limited to people whose names appear as landowners. Tenant farmers and sharecroppers are included, although they may need to provide suitable evidence of their cultivation arrangement. The bank checks the applicant’s records and determines the credit amount under its lending rules. Press Information Bureau+1

    Documents required for KCC application

    Prepare the following documents and details before applying:

    • Completed KCC application form.
    • Identity proof, such as Aadhaar or another accepted government ID.
    • Address proof, as required by the bank.
    • Passport-size photographs.
    • Landholding records certified by the revenue authority, where applicable.
    • Details of crops grown and the area under cultivation.
    • Bank account information.
    • Documents supporting tenancy or sharecropping arrangements, where applicable.
    • Additional security documents if required for the proposed loan amount.

    The government has described a simplified one-page KCC application form. It may contain basic details already available through a farmer’s PM-KISAN records, but applicants still need to provide land records and crop information. Common Service Centres (CSCs) have also been authorised to help farmers complete and digitally transmit applications to banks. Press Information Bureau+1

    How to apply for Kisan Credit Card Yojana

    You can apply through a participating bank or, where supported, through its online application facility.

    Step 1: Identify the right bank. Contact the bank, regional rural bank or cooperative institution serving your farming area. Ask whether it offers KCC for your type of agricultural activity.

    Step 2: Get the application form. Request the KCC form from the branch or download it from the bank’s official website if an online form is available.

    Step 3: Fill in farm details. Enter your personal information, land details, crop pattern, acreage and estimated credit needs.

    Step 4: Attach supporting documents. Submit identity and address proof, land records, crop details and any documents that establish tenancy or sharecropping.

    Step 5: Complete bank verification. The bank checks the applicant’s details, land or cultivation records, crop requirements and repayment capacity. It may ask for additional documents or clarification.

    Step 6: Review the sanction terms. If approved, check the credit limit, interest rate, repayment schedule, security conditions and any applicable charges before accepting.

    Step 7: Activate and use the facility. Follow the bank’s instructions to activate the card or account. Use the funds for the approved agricultural and allied purposes.

    You can explore the scheme through the Government of India’s myScheme Kisan Credit Card page. For a bank-specific application and document list, visit your lender’s official website. myScheme+2

    Common mistakes farmers should avoid

    • Applying without updated land or cultivation records: Differences in names, acreage or crop details can delay verification.
    • Assuming every applicant receives the same limit: The bank calculates the limit based on the applicant’s needs and local scale of finance.
    • Treating the card as free money: KCC is credit, not a grant. Repayment is required.
    • Assuming all borrowing receives a 4% rate: The prompt repayment benefit and interest support have conditions and limits.
    • Ignoring the repayment date: Repayment is linked to the crop and marketing period under the sanctioned facility.
    • Using unofficial agents: Submit forms through the bank or authorised CSC route. Do not pay unknown people who promise guaranteed approval.

    An illustrative example

    Suppose a farmer cultivates two acres of land and needs money for seeds, fertiliser and labour before the next crop season. The farmer applies for KCC through a local bank and submits land records, crop details and identity documents. The bank reviews the acreage and local scale of finance, then decides the suitable credit limit.

    The farmer can use the approved facility for eligible farm expenses and repay it according to the bank’s crop-linked schedule. The example is illustrative: actual loan amounts, interest and approval depend on the bank’s assessment and current rules.

    Frequently asked questions

    1. Can tenant farmers apply for KCC?

    Yes. Tenant farmers, oral lessees and sharecroppers are included in the scheme. They must provide the documents or evidence required by the lending bank.

    2. What is the maximum KCC loan amount?

    There is no one fixed amount for every farmer. The sanctioned limit depends on cultivation area, crop pattern, local scale of finance and the bank’s assessment. Government updates have also changed certain MISS limits, so check the current applicable terms.

    3. Is KCC collateral-free?

    The government reported a collateral-free credit limit of ₹2 lakh per borrower effective from 1 January 2025. Banks may apply specific conditions and security requirements above the applicable threshold.

    4. Can KCC be used for dairy or fisheries?

    Yes. The scheme covers eligible allied activities, including dairy and fisheries, subject to the lender’s assessment and the relevant credit rules.

    5. Is the Kisan Credit Card a subsidy?

    No. It is a credit facility. Eligible borrowers may receive interest support or a prompt repayment incentive under government rules, but the borrowed amount must still be repaid. Press Information Bureau+2

    Apply through an official bank or government source

    Start by checking your eligibility and gathering your land and crop records. Visit the Government of India’s myScheme KCC page to review scheme information, then contact your bank for the current application form, loan limit and interest terms. Do not sign until you understand the repayment schedule and the exact interest support available for your loan.

  • Salmonella Outbreak Linked to Jalapeño Peppers from Mexico: 488 Illnesses Evaluated Across 34 U.S. States

    Salmonella Outbreak Linked to Jalapeño Peppers from Mexico: 488 Illnesses Evaluated Across 34 U.S. States

    Overlook

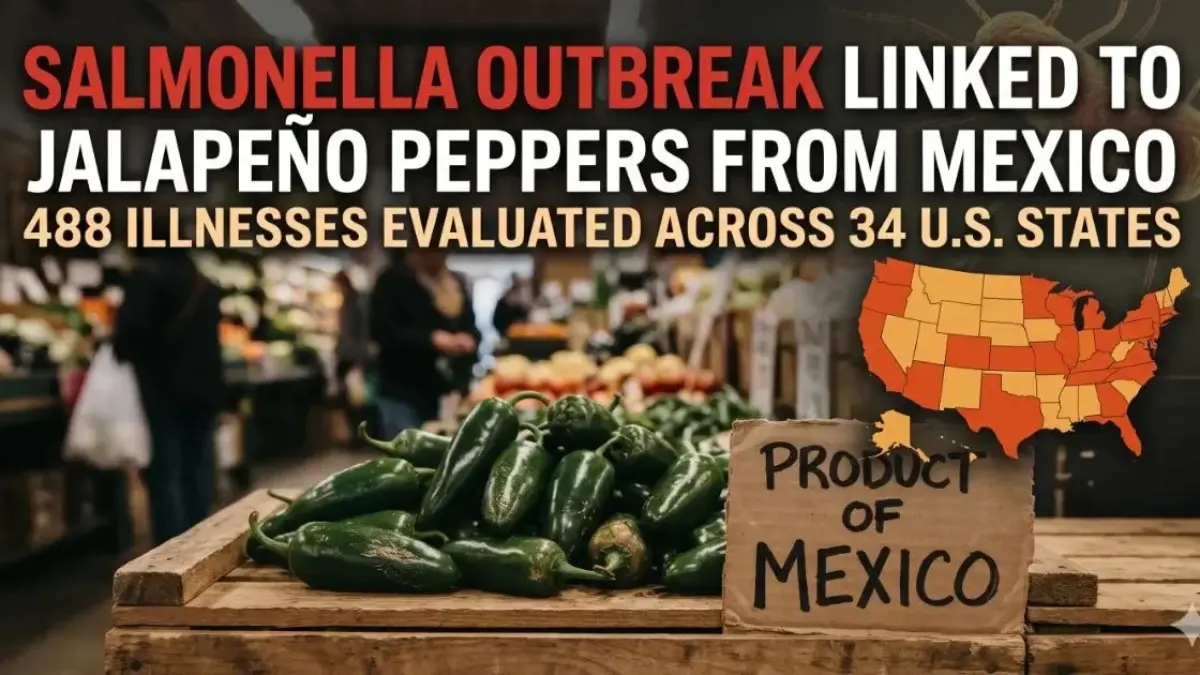
    A multistate outbreak of Salmonella Javiana infections in the United states(US) linked to contaminated jalapeño peppers imported from Sinaloa, Mexico, and distributed by Coast Citrus Distributors. The investigation, conducted by the U.S. Food and Drug Administration (FDA), Centers for Disease Control and Prevention (CDC), and state and local public health authorities, reported 488 illnesses across 34 states.

    CDC’s final investigation update published on October 2, 2026, the outbreak resulted in 65 hospitalizations and no reported deaths, thankfully. The agency officially declared the outbreak over after reviewing epidemiological, laboratory, and food-traceback information.

    The infected jalapeño peppers supplied to wholesalers, restaurants, food distributors, and food service companies in US. Numerous businesses subsequently initiated additional recalls after using the affected peppers as ingredients in prepared foods, sauces, dips, and other products such as salsa,guacamole, etc.

    How the Salmonella Outbreak Was Identified

    Salmonella Outbreak

    The investigation identified jalapeño peppers imported from Sinaloa, Mexico, and distributed by Coast Citrus Distributors as the likely source of the outbreak.

    Health authorities collected epidemiological information from people who became ill and examined their food consumption histories. Among 308 individuals interviewed, 281 (91%) reported eating at a Mexican-style restaurant during the week before becoming ill.

    The restaurants mentioned in the investigation included Chipotle Mexican Grill and QDOBA. Investigators identified 36 illness clusters associated with 31 Chipotle locations across seven states and five QDOBA locations across two states.

    Coast Citrus Distributors Initiates Jalapeño Recall

    Coast Citrus Distributors initiated recall actions to remove potentially contaminated jalapeño peppers from the supply chain.

    On July 22, 2026, the company initiated a limited recall involving jalapeño peppers packaged in bulk generic Coast Tropical packaging.

    On August 5, 2026, the company agreed to recall the remaining jalapeños imported from Sinaloa, Mexico, that were implicated through epidemiological and traceback information.

    USDA Issues Additional Public Health Alert for Meat and Poultry Products

    The U.S. Department of Agriculture’s Food Safety and Inspection Service (FSIS) also issued a public health alert on August 8, 2026.

    The alert concerned various meat and poultry products containing FDA-regulated jalapeños that had been recalled because of potential Salmonella contamination.

    The agency warned that affected products could remain in household refrigerators, freezers, or retail establishments. Consumers were advised not to consume products identified in the alert, while retailers were instructed not to sell or serve them.

    Importantly, FSIS reported that there were no confirmed illnesses associated with consumption of the FSIS-regulated meat and poultry products containing the affected jalapeños at the time of its announcement.

    Symptoms and Health Risks of Salmonella Infection

    Salmonella is a foodborne bacterium that can cause an intestinal infection known as salmonellosis. People generally develop symptoms within 12 to 72 hours after consuming contaminated food.

    Common symptoms include:

    • Diarrhea
    • Fever
    • Abdominal cramps

    Symptoms generally last four to seven days, and many infected individuals recover without specific medical treatment.

    However, severe infections can occur, particularly among young children, older adults, and individuals with weakened immune systems. Anyone experiencing concerning symptoms after consuming a potentially affected product should contact a healthcare professional.

    The CDC also reported that laboratory analysis identified predicted antimicrobial resistance in samples from three individuals. These findings may be relevant to treatment decisions if antibiotics are required, although most people with Salmonella infections recover without antibiotic treatment.

    Current Investigation Status

    As of October 2, 2026, the CDC declared the multistate Salmonella Javiana outbreak linked to jalapeño peppers from Sinaloa, Mexico, over. The FDA also closed its outbreak investigation.

    The recalled fresh jalapeños distributed by Coast Citrus Distributors are no longer for sale and are past their shelf life, according to the FDA. However, some downstream products made using the affected peppers may have longer shelf lives, making it important for consumers to check the consolidated recall information.

    Although investigators identified a common grower in Sinaloa as the likely source, the FDA reported that it could not determine the specific route or source of contamination during its investigation.

    The outbreak highlights the importance of food traceability, supplier verification, microbiological surveillance, and coordinated recall procedures throughout the food supply chain.

    Conclusion

    The 2026 Salmonella Javiana outbreak associated with jalapeño peppers imported from Mexico resulted in 488 reported illnesses and 65 hospitalizations across 34 states. Although the CDC has declared the outbreak over, the associated product recalls remain important for consumer awareness and food safety.

  • Hello world!

    Welcome to WordPress. This is your first post. Edit or delete it, then start writing!